How A Credit Card Works
Okay, let’s talk about the little plastic rectangle in your wallet that feels like a magic wand, but is actually more like a very persuasive gremlin. A credit card isn’t free...
Okay, let’s talk about the little plastic rectangle in your wallet that feels like a magic wand, but is actually more like a very persuasive gremlin. A credit card isn’t free money. It’s a short-term loan from a bank that you swear you’ll pay back next month, but you probably won’t remember exactly how much you spent on those novelty socks.
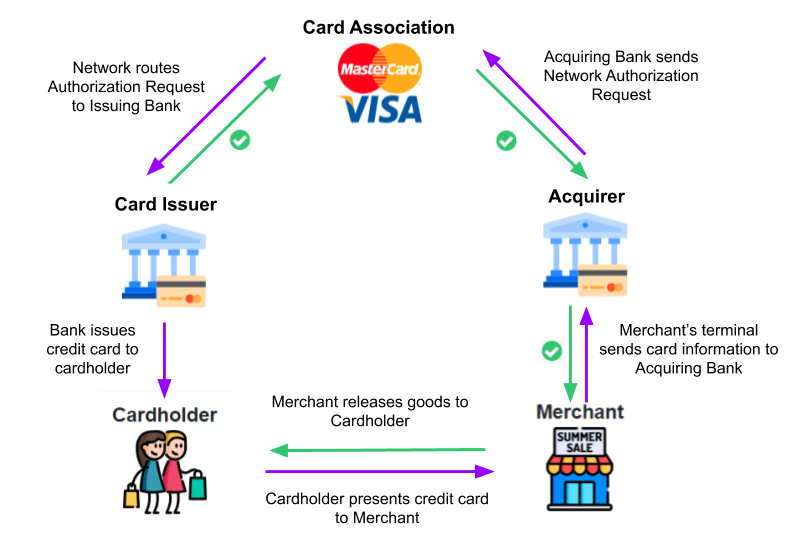
Here’s the core secret: when you swipe that card, the bank pays the store for you right then and there. You, in turn, owe the bank. This is called credit, which is just a fancy word for “the bank’s faith that you’re not a complete deadbeat.”
You get a credit limit, which is the maximum amount of money the bank trusts you to borrow before they start having second thoughts about your life choices. If you go over that limit, you’ll get hit with a fee that feels like a personal insult from a robot.
The Billing Cycle: Your Month of Reckoning
Every month, the bank sends you a statement. This is a brutally honest list of every taco, gas station coffee, and impulse Amazon purchase you made. It’s like a financial diary written by a judgmental ghost.
You then have a grace period—usually about three weeks—to pay that entire balance in full. Do that, and you’ve successfully convinced the bank you’re an adult, and they charge you zero interest. It’s the only time in life you can borrow money for free and not feel like you’re getting away with a crime.
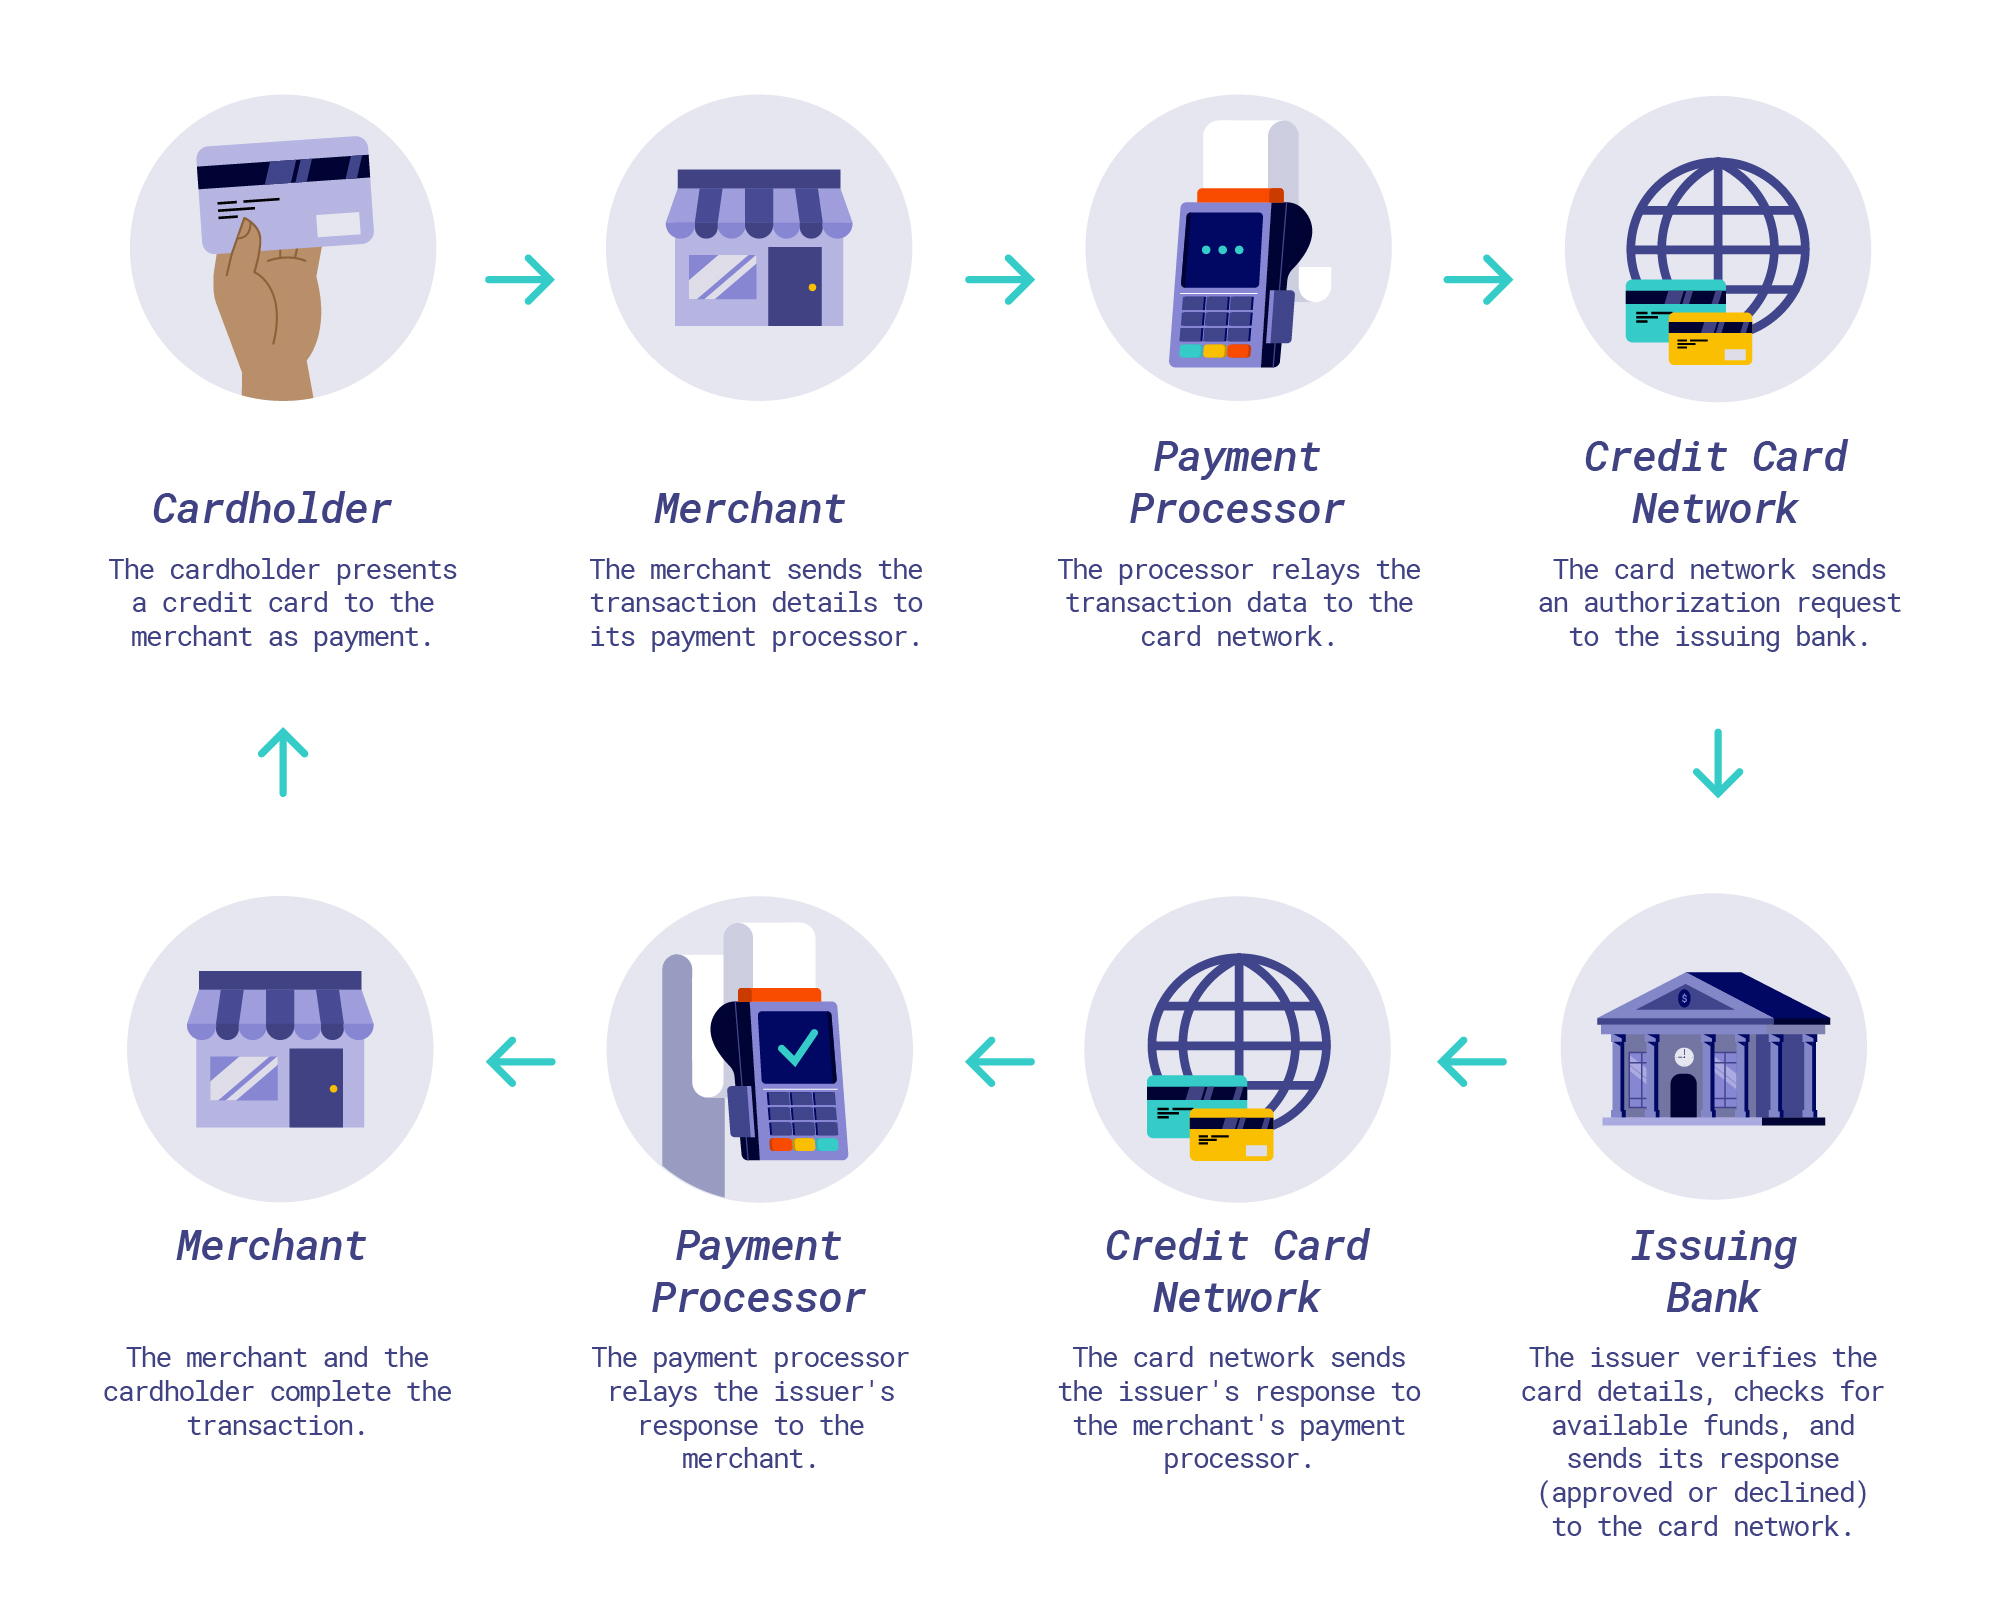 How the Credit Card Payment Process Works | Corporate Tools®
But if you only pay the minimum payment (usually a measly 2% of what you owe), you are playing a dangerous game. The remaining balance doesn’t vanish; it just sits there, smirking, waiting to collect interest.
The Vicious Interest Monster
That interest is called the APR (Annual Percentage Rate), and it can be a terrifying number like 22% or, if you’ve made some poor choices, a soul-crushing 29%. This is the bank’s way of saying, “Thanks for not paying us back! Here’s a fee for the privilege of our patience.”
Interest compounds daily. That means the bank calculates what you owe every single day, adding a tiny amount that grows into a monster. It’s like a snowball rolling down a hill, except the snowball is made of debt and the hill is your bank account. Surprising fact: If you only pay the minimum on a $5,000 balance at 18% APR, it will take you over 20 years to pay it off and cost you nearly $4,000 in interest. That’s a car you paid for twice.
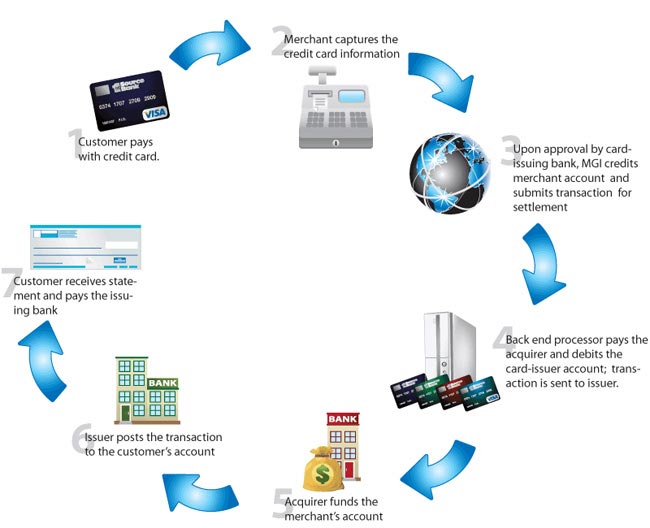 Credit Cards That Work
The Perks and the Pitfalls
So why use them at all? Because they come with rewards. Every time you spend money, the bank gives you back a tiny fraction of it in the form of “cash back” or “points.” It’s like the bank is bribing you to use their loan, which is fine as long as you don’t fall for the trap.
Credit cards also offer purchase protection and fraud liability. If someone steals your card and buys a giant inflatable flamingo, you won’t usually have to pay for that flamingo. That’s a superpower your debit card doesn’t have. Another fun fact: The first universal credit card was the Diners Club card in 1950, and it was literally just a piece of cardboard. People used it to pay for meals, and then the bill collector would drive to your house to collect.
Here’s the golden rule: a credit card is a tool, not a toy. If you treat it like a second salary, you’ll end up paying for last year’s vacation for the next decade. But if you pay your balance in full every month, you get free money, better fraud protection, and a credit score that makes landlords swoon. Just remember: the gremlin is always hungry. Don’t feed it after midnight.
