Is $10 Million Enough To Retire At 30
The dream of retiring at 30—free from the daily grind, with decades of life ahead—is one of the most powerful fantasies of modern life. It promises true autonomy: the ability...
The dream of retiring at 30—free from the daily grind, with decades of life ahead—is one of the most powerful fantasies of modern life. It promises true autonomy: the ability to spend your mornings on a hobby, your afternoons traveling, and your evenings with loved ones, all without worrying about a paycheck. For many, this isn't just about leisure; it's about reclaiming time, the most non-renewable resource we have. The question that inevitably follows is simple yet daunting: Can $10 million actually make that dream a reality?
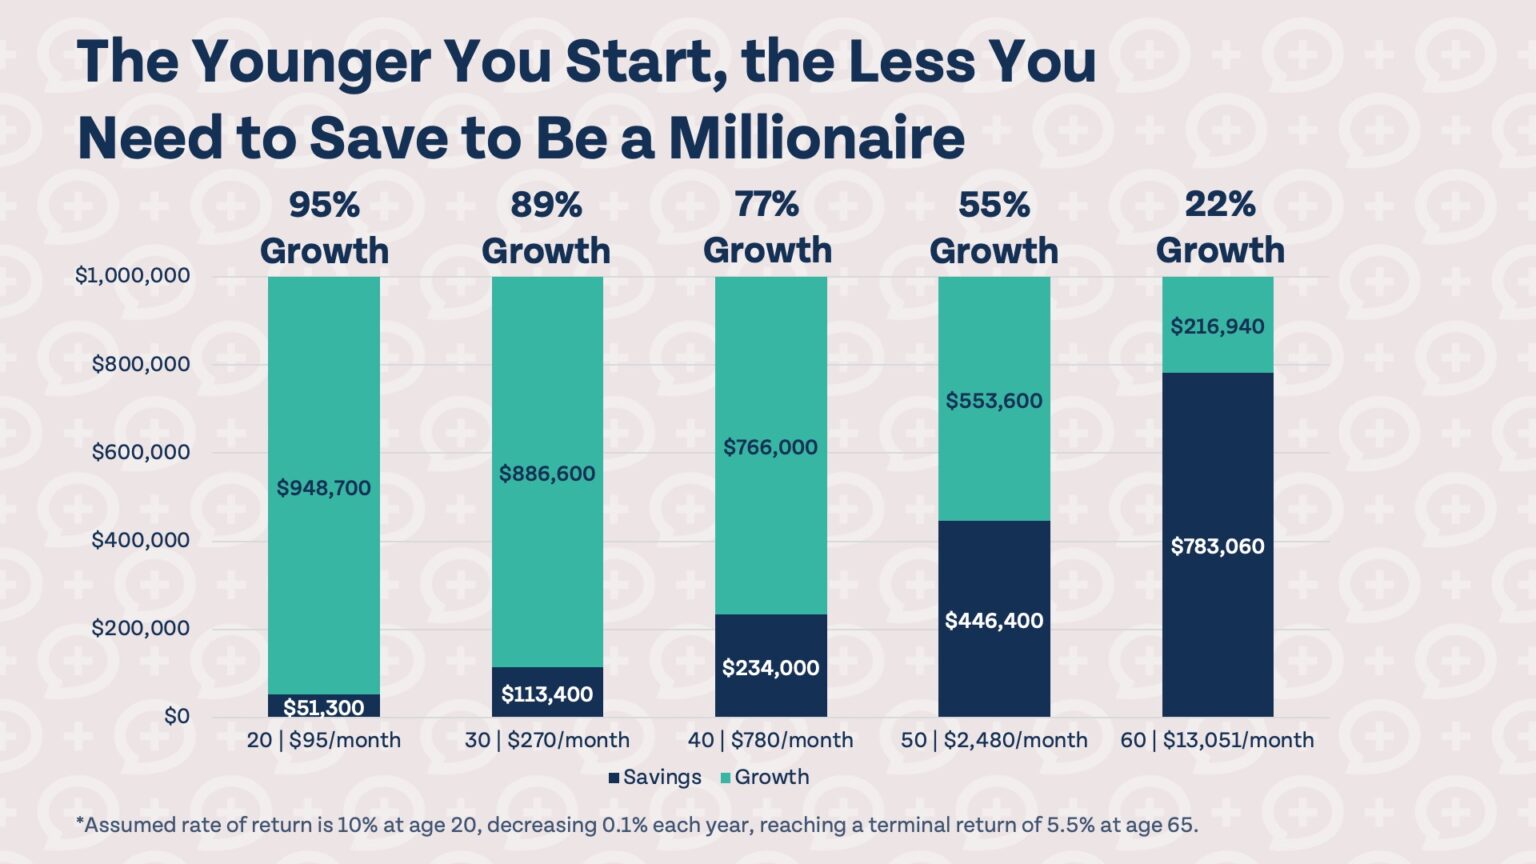
The key purpose of understanding this financial threshold is to move from abstract wishful thinking to practical, data-driven planning. A $10 million nest egg isn't just a pile of cash; it's an engine designed to generate income for potentially 60 years or more. For everyday life, getting this right means the difference between a carefree early retirement and a constant, gnawing fear of running out of money. The benefits are immense: peace of mind, the freedom to pursue passion projects, and the ability to withstand life's unexpected storms without returning to the workforce.
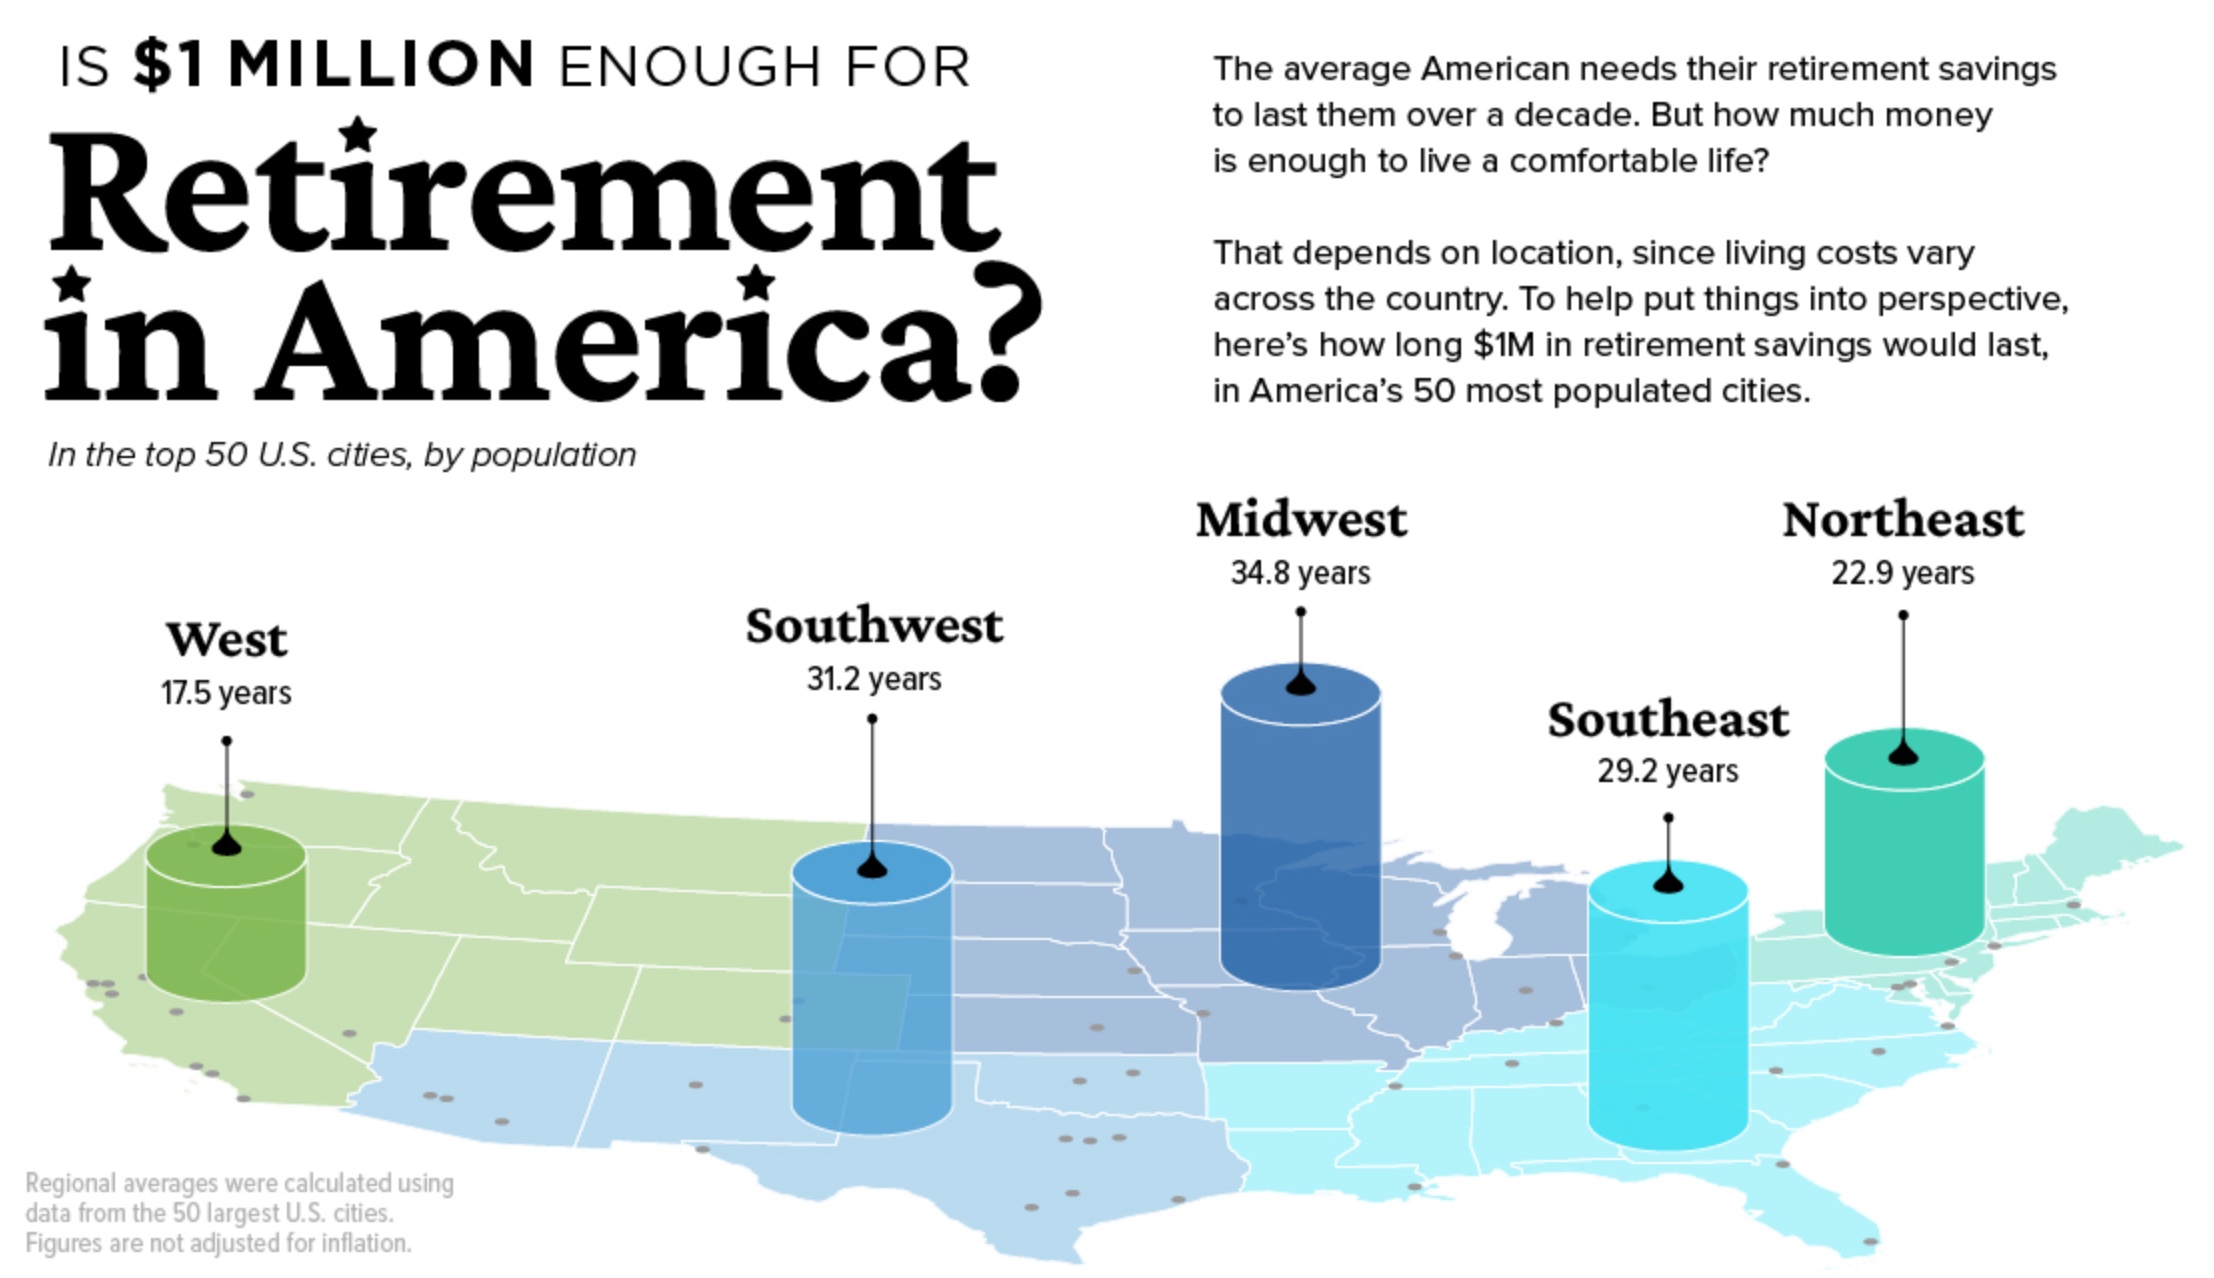
To put this in context, let's consider a simple scenario: the 4% rule. This widely cited guideline suggests you can safely withdraw 4% of your portfolio annually, adjusted for inflation, without depleting it over 30 years. For $10 million, that's $400,000 per year in pre-tax income. For a 30-year-old with no mortgage, this provides an extraordinarily comfortable lifestyle—far beyond what most households earn. However, the real challenge isn't the annual amount, but the duration. Over a 70-year retirement, even a small market downturn early on, combined with higher inflation, can force you to cut spending drastically or take on sequence-of-returns risk.
Must Read
Another crucial factor is lifestyle inflation. A $10 million fund can easily support a life of global travel and fine dining, but only if you resist the urge to upgrade everything. For example, if you buy a $5 million home and a $200,000 car, your annual withdrawal rate might jump to $300,000—still generous, but a sharp cut from the original plan. Conversely, a simpler lifestyle—living in a modest home, cooking at home, and taking a few nice trips a year—could keep your spending at $150,000 annually. At that rate, your 4% withdrawals leave a massive safety buffer, and your money is more likely to grow faster than you spend it.
Healthcare costs are another hidden pitfall. At 30, you are not eligible for Medicare in the U.S., meaning you must purchase private insurance for decades. A serious illness or chronic condition could easily cost $20,000 to $50,000 per year out of pocket. Factoring in these unpredictable, rising costs is essential. The benefit of $10 million here is that you can afford the highest-tier "Cadillac" health plans, but ignoring this line item in your budget could derail even the most robust retirement plan.
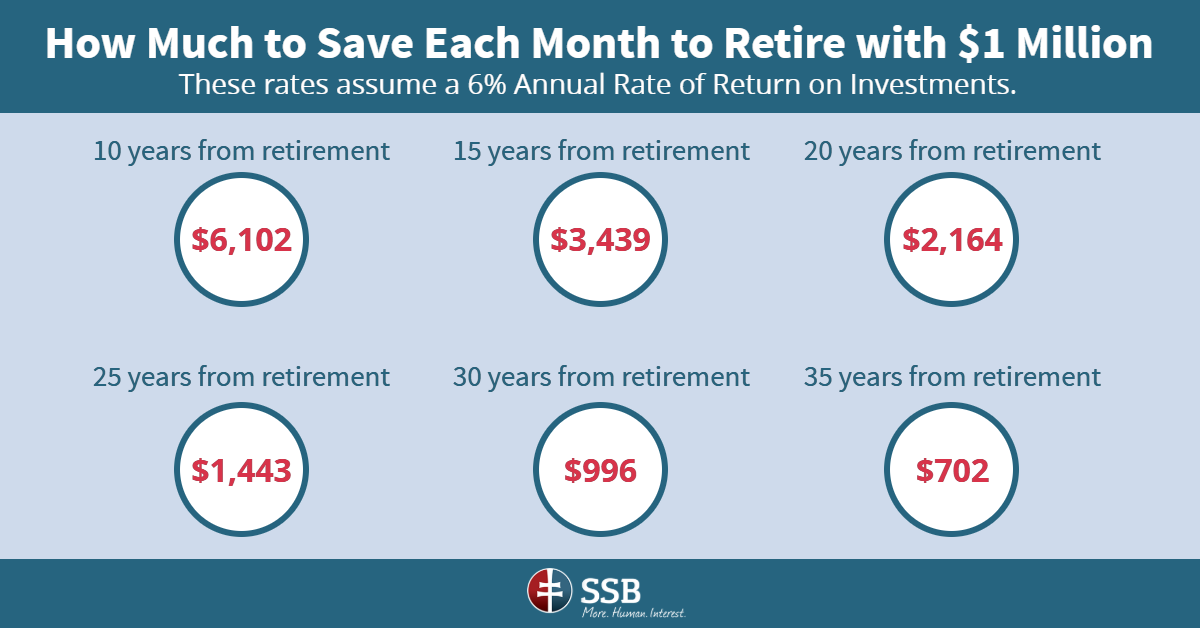 How Much Money Should Be In Retirement By 30 – WAHZ
To explore this concept for yourself, start with these simple tips. First, use a free online retirement calculator that allows you to input different withdrawal rates and time horizons. Play with conservative scenarios: assume a 3% withdrawal rate and a 50-year retirement. Second, track your current spending for three months. The number that shocks you is your "lifestyle cost"—now multiply it by 30 to see if $10 million feels like a fortress or a fragile castle. Finally, consider adding a side income stream, even in retirement. A modest freelance project or rental property can act as a powerful buffer, reducing the pressure on your principal and letting your $10 million compound in peace.
In conclusion, $10 million is more than enough to retire at 30, but only if you approach it with discipline and realism. The money is a tool, not a magic wand. For those who can control their spending, plan for healthcare, and ride out market volatility without panic, that sum offers a life of extraordinary freedom. For anyone tempted by unlimited spending, it can vanish faster than expected. The true value of $10 million lies not in the number, but in the lifestyle structure you build around it.